
Chapter 6.5
The Trial Balance
The accountant's first report at every month- and year-end: every account's debit or credit balance on a date, proof that the books balance, and a worksheet for proposed adjustments that are not yet posted.
When you finish this chapter you will be able to:
- Say what a trial balance proves, and what it does not.
- Run it as of any date, with or without closing entries.
- Use the worksheet adjustment columns to try out entries before posting them.
What it proves
Every entry has equal debits and credits, so the debit balances of all accounts must equal the credit balances. The trial balance lists them side by side and totals both columns. Equal totals prove the books are arithmetically in balance.
As the report's own note says, equal debits and credits do not show that every transaction was entered, or entered in the right account. A fuel receipt posted to Meals still balances. That is what reviewing accounts and reconciling (Chapter 4.4) are for.
Run and read it
Reports → Trial Balance.
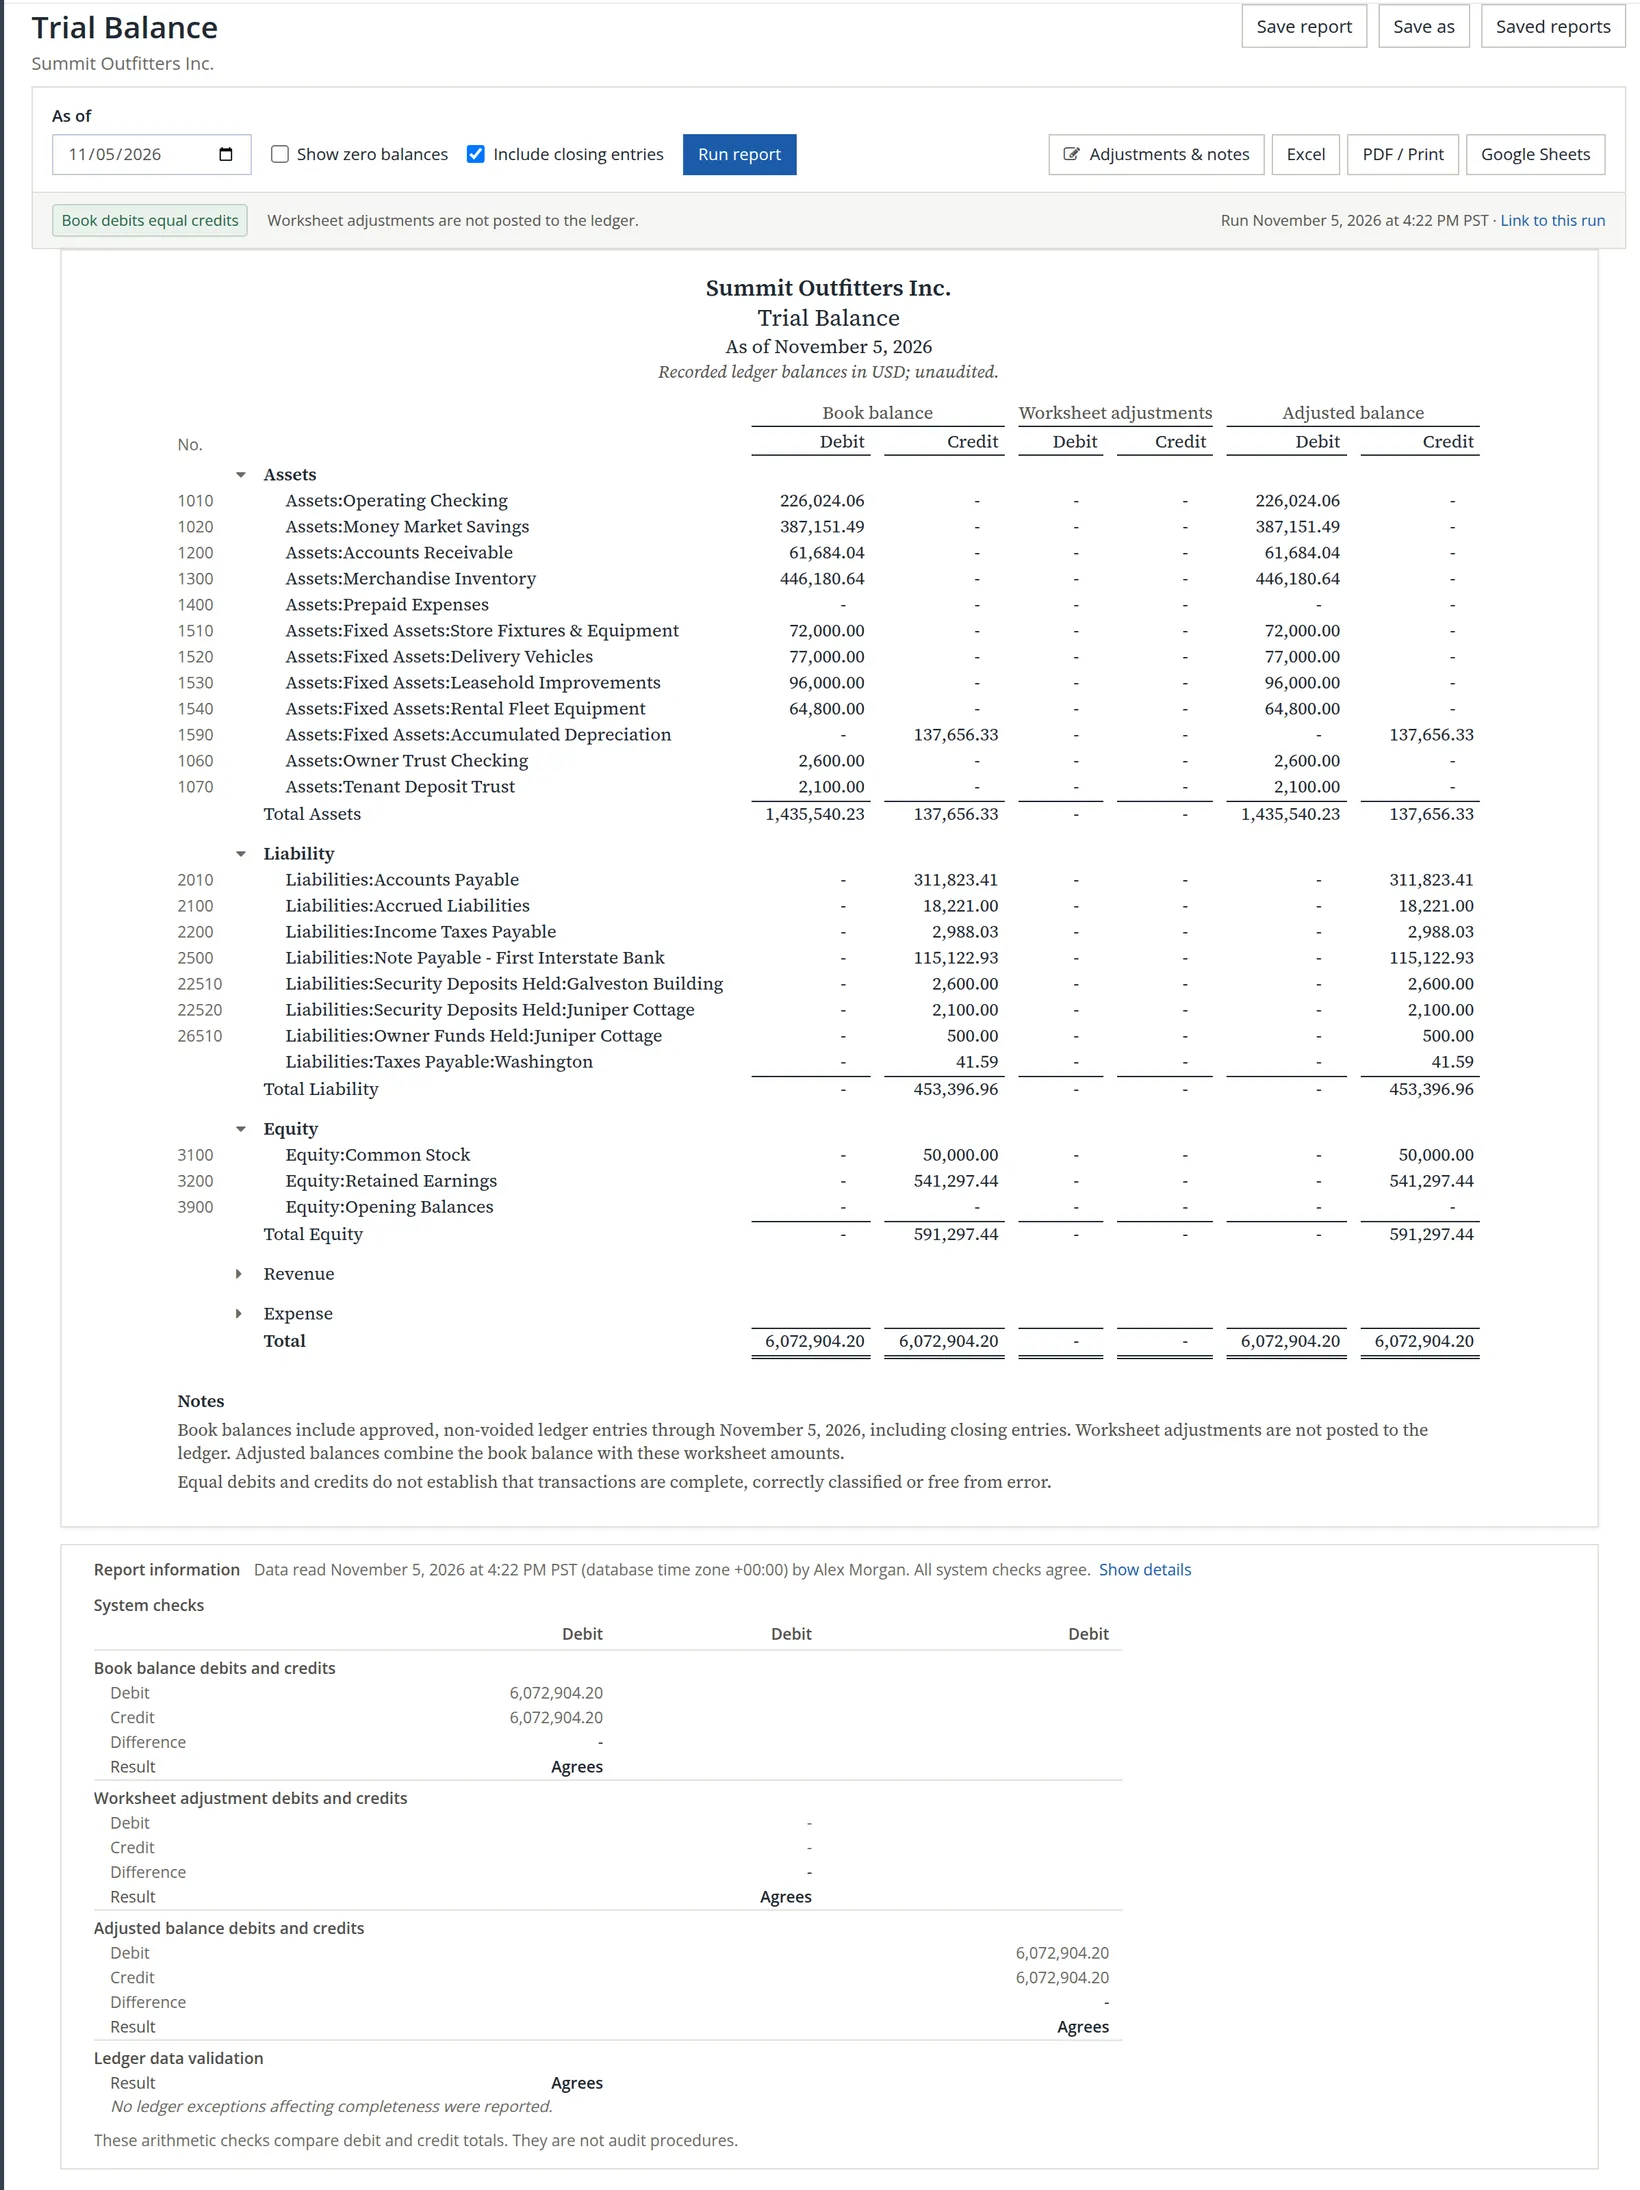
- 1
Choose the date 1 and options
Show zero balances 2 lists accounts with nothing in them. Include closing entries 3: leave ticked for the books as they stand; untick to see the year before closing. Then Run report 4.
- 2
Check the badge 6 and the totals 10
Book debits equal credits: $6,072,904.20 on each side. The system checks 11 repeat the test for the book balances, the worksheet and the adjusted balances, and check the ledger data itself.
- 3
Read the three column pairs
Book balance 7 is the ledger. Worksheet adjustments 8 are proposed entries. Adjusted balance 9 is the two combined. A long trial balance reads more easily one group at a time: the triangle beside a group 12 folds it shut, and the Total line still counts it. In the picture Revenue and Expense are folded, and the total is unchanged.
- 4
Try out adjustments 5
Adjustments & notes lets an accountant enter year-end adjustments (depreciation, accruals, reclassifications) and see their effect without posting anything. Once agreed, post them as journal entries (Chapter 5.2).
Most tax preparers start from the trial balance. Export it to Excel as of the year-end date, with closing entries unticked, and you have answered their first request before they make it. Save report keeps the settings for next year.
Check your understanding
1. The trial balance totals agree. Can you be sure every expense is in the right account?
Answer
No. Equal totals prove only that debits equal credits.
2. Are worksheet adjustments posted to the ledger?
Answer
No. They show on the report only, until you post them as journal entries.
Notes
- Since November 2026 the Trial Balance has its own row, Trial Balance, in Users and permissions (Chapter 15.7). Members who may read the Balance Sheet were given it: viewers, bookkeepers, accountants and auditors read it; payroll clerks, employees and stakeholders do not. Earlier editions said only the owner could run it, and took the pictures from Summit Gear Repair. The practice user is a member of Summit Outfitters Inc. with the permission, so the pictures now come from Summit Outfitters itself. ↑